Under the Spotlight: Nokia Corp ($NOK)
Nokia left phones behind years ago. Now AI data-centre demand is putting the former handset giant back on investors’ radar.
ICYMI: Do your own research and make your own decisions. This article drills down on a specific company, however, it is not a recommendation to invest in the company and should not be taken as financial advice. Got a stock you want covered? Tell us here.
Nokia ($NOK) built its name on the virtually indestructible 3310. More than a decade after leaving phones behind, the Finnish company is reinventing itself again, this time as a supplier of the networking infrastructure behind AI data centres.
Nvidia’s ($NVDA) US$1B investment last year gave new credence to that part of the business, while Nokia’s latest results showed sales to AI and cloud customers more than double in Q2, with new orders reaching €2.8B (~US$1.4B).
But those same results showed AI remains a small part of the business, free cash flow was negative and the stock has already enjoyed a major rerating.
So, is Nokia becoming a genuine AI infrastructure winner, or has the market dialled in the good news early? Let’s put it under the spotlight.
From handsets to hyperscalers
Nokia stopped making the phones most people remember in 2014, when it sold almost all of its Devices & Services business to Microsoft.
Since then, it has rebuilt itself around telecommunications infrastructure. Its 2025 acquisition of Infinera expanded Nokia’s optical networking business, giving it a stronger position in the systems that carry data between AI data centres.
Nokia doesn’t make the chips powering AI models. It sells part of the plumbing that lets those chips, servers and data centres talk to one another.
Telco pays the bills
Nokia has three operating divisions, led by Mobile Infrastructure, followed by Network Infrastructure and the much smaller Portfolio Businesses segment.
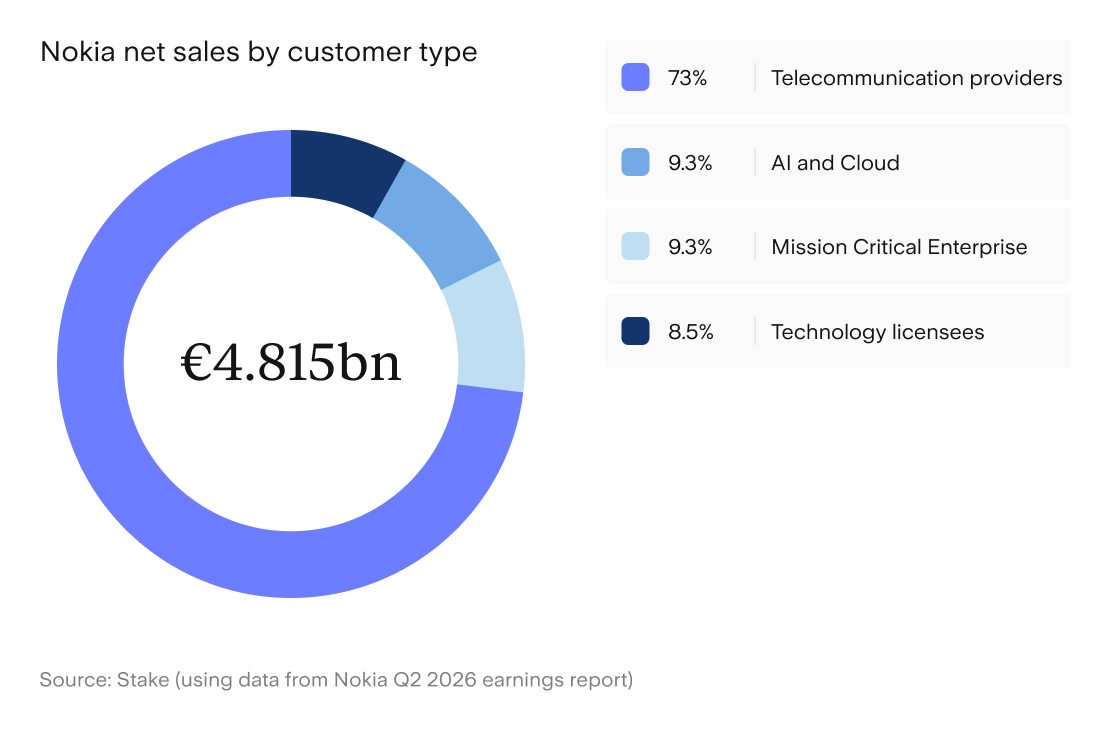
But the cleanest way to see how the company is changing is to look at who’s buying the products. Telcos are still Nokia’s main customers, while AI and cloud customers remain a much smaller but far faster-growing group.
The telco customer group generated €3.51B in Q2, around 73% of Nokia’s €4.82B in net sales. AI and cloud customers contributed €446M, or 9.3% of revenue, however jumped 103% year-on- year, outpacing all other segments.
The AI signal
The standout figure in Nokia’s latest results was €2.8B in new AI and cloud orders, with management expecting roughly half to convert into revenue over the next 12 months.
That should gradually reduce Nokia’s reliance on telco customers, although telcos will remain its largest customer group for some time. The order intake is not revenue yet, and Nokia still needs to turn that pipeline into completed deliveries.
Nokia says the main challenge is now filling demand, with component shortages limiting how quickly it can turn orders into delivered equipment.
For now, most of the AI opportunity is coming from data-centre networking. AI-RAN, which uses AI and accelerated computing to improve mobile networks, is the longer-term bet being developed with Nvidia.
A rebound, then slower climb
Nokia is a long way from its glory days in mobile phones, but its revenue has recently started moving in the right direction again.
Revenue fell in 2024, with most of the decline linked to a sharp slowdown in India after its rapid 5G rollout. It then rose 7.9% in U.S.-dollar terms to US$22.4B in 2025, helped by stronger Network Infrastructure sales and the addition of Infinera.
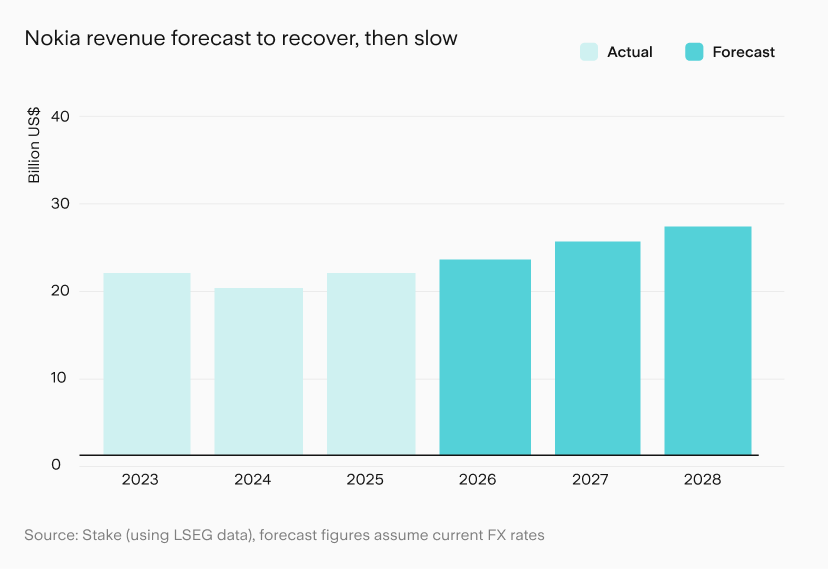
Analyst forecasting on LSEG points to revenue climbing 11% to US$24.8B in 2026, before growth slows into 2028. That points to a solid recovery, but not the runaway growth investors might expect from a pure AI stock.
Still, Nokia expects profit to grow faster than revenue over the next few years. Its faster-growing Network Infrastructure division is targeting a margin of 13% to 17% by 2028, up from 8.1% in Q2, and group operating profit is expected to reach up to €3.2B.
Valuation check
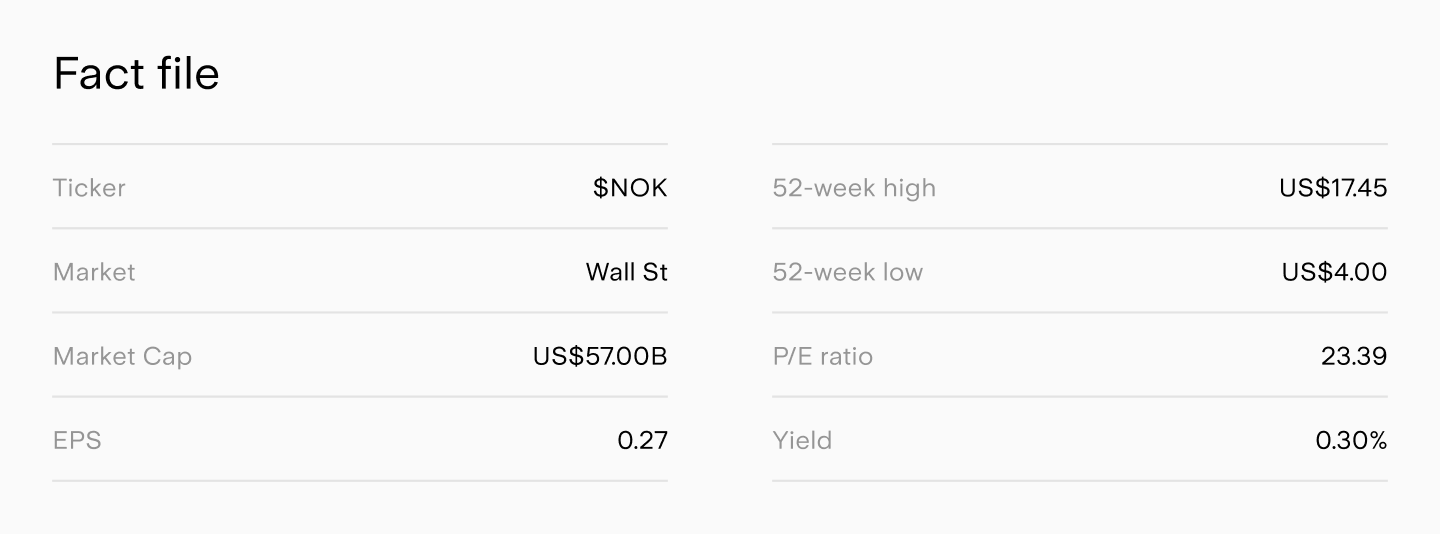
Nokia trades at roughly 24 times forecast FY26 earnings, falling to around 20 times FY27 earnings and 17 times FY28 earnings.
U.S. telecom-equipment companies trade on an average forward P/E of 39.5, versus 27.7 for the broader U.S. market. That makes Nokia look reasonable beside the sector, although it remains well above its own three-year normalised average of 13.7 times.
The multiple comes down quickly if next earnings meet forecasts. Investors are still paying upfront for the turnaround to work.
Analysts are broadly positive about $NOK, with 10 of the 12 listed on LSEG rating the stock a ‘buy’ or ‘strong buy’ and two a ‘hold.’ The average price target is US$14.49, around 49% above its last traded price.
Is it a buy?
At today’s valuation, Nokia’s investment case depends on the company delivering the growth already reflected in its share price.
AI and cloud sales have doubled, Network Infrastructure is growing faster, margins are expanding and Nvidia has put real money behind its partnership.
But AI remains a minority of revenue, while telecom providers still contribute 73% of sales. Q2 free cash flow was negative €732M, largely due to a €1.15B working-capital outflow. Restructuring charges are also expected to reach €800M this year.
For Nokia to justify its new valuation, investors need to see the order pipeline convert into revenue, margins keep climbing and accounting profit turn into sustainable free cash flow.
The Q2 result makes Nokia’s AI story worth taking seriously. The next few quarters will show whether its earnings can live up to the 3310’s reputation.
This not financial advice nor a recommendation to invest in the securities listed. The information presented is intended to be of a factual nature only. Past performance and forecasts are not a reliable indicator of future performance. The value of your investments can go down as well as up and you may receive back less than your original investment. The author of this article and other employees of Stakeshop Pty Ltd may hold positions or have financial interests in the company (or companies) discussed above. Stakeshop Pty Ltd does not accept any liability for any decisions you may make if you consider and/or use any of the information contained in this article. As always, do your own research and consider seeking financial, legal and taxation advice before investing. This email is subject to our Disclaimers, Terms and Conditions and Privacy Policy. If you are not the intended recipient of this communication, you are not authorised to read, disclose, reproduce, disseminate or otherwise use this information. While we have taken precautions to ensure that no viruses are present in this email, you should rely on your own virus checking systems and processes. You can contact us at support@hellostake.com.
Senior Markets Commentator
Kylie Purcell is an investments analyst and finance journalist with over a decade of experience covering global markets, investment products and digital assets. Her commentary has been featured in publications including the Australian Financial Review, Yahoo Finance and The Motley Fool. She has a Masters Degree in International Journalism from Cardiff University and a Certificate of Securities and Managed Investments (RG146).
Subscribe
By subscribing, you agree to our Privacy Policy.