Under the Spotlight: Exxon Mobil ($XOM)
As Trump lays plans for Venezuela’s vast reserves, will America’s biggest oil company play ball?
ICYMI: Do your own research and make your own decisions. This article drills down on a specific company, however, it is not a recommendation to invest in the company and should not be taken as financial advice. Got a stock you want covered? Tell us here.
The fall of Venezuela’s long-entrenched president has reignited hopes that U.S. oil majors could reclaim access to the world’s largest crude reserves.
President Trump said it straight. ‘We’re going to have our very large United States oil companies… go in, spend billions of dollars,” he told reporters just hours after President Nicolás Maduro was captured. ‘We are going to take back the oil.’
For the biggest of these, Exxon Mobil ($XOM), returning to Venezuela would be as much symbolic as strategic. Exxon was central in building the country’s oil industry from the 1920s until it was pushed out in the 2000s under then President Hugo Chávez.
Markets saw the potential. The S&P 500 energy index rose to its highest level since March last year, as shares in U.S. oil companies Exxon Mobil, Chevron ($CVX) and ConocoPhillips ($COP) jumped on the news. Chevron, the only remaining U.S. oil firm left in the country, is the clearest winner. Its shares jumped 5.5%, while Exxon rose 2.2%.
But days on the reality of Trump’s plan is sinking in. Even if Exxon could re-establish operations, the impact on its bottom line is unclear given the huge costs and falling oil prices.
With the situation evolving faster than analysts can do the maths, investors will need to look beyond the news to understand Exxon Mobil’s potential.
Black gold
A return to Venezuela’s vast reserves could materially benefit Exxon, which has long argued that billions of dollars in assets were expropriated during the country’s nationalisation.
But more than a decade of underutilised infrastructure would take billions to restore – and oil companies expected to shoulder the cost. For Exxon Mobil, which operates on six continents, Venezuela is no longer essential. The company has long since diversified its operations and revenue beyond the country.
In fact, after exiting in 2007, Exxon simply shifted operations to neighbouring Guyana. A decade on, that bet has paid off, with production hitting a record 700K barrels a day last quarter. Output in America’s oil-rich Permian Basin also reached record levels, at nearly 1.7 million barrels per day, supported by improved operating efficiencies. Both regions are forecast to lift production again this year.
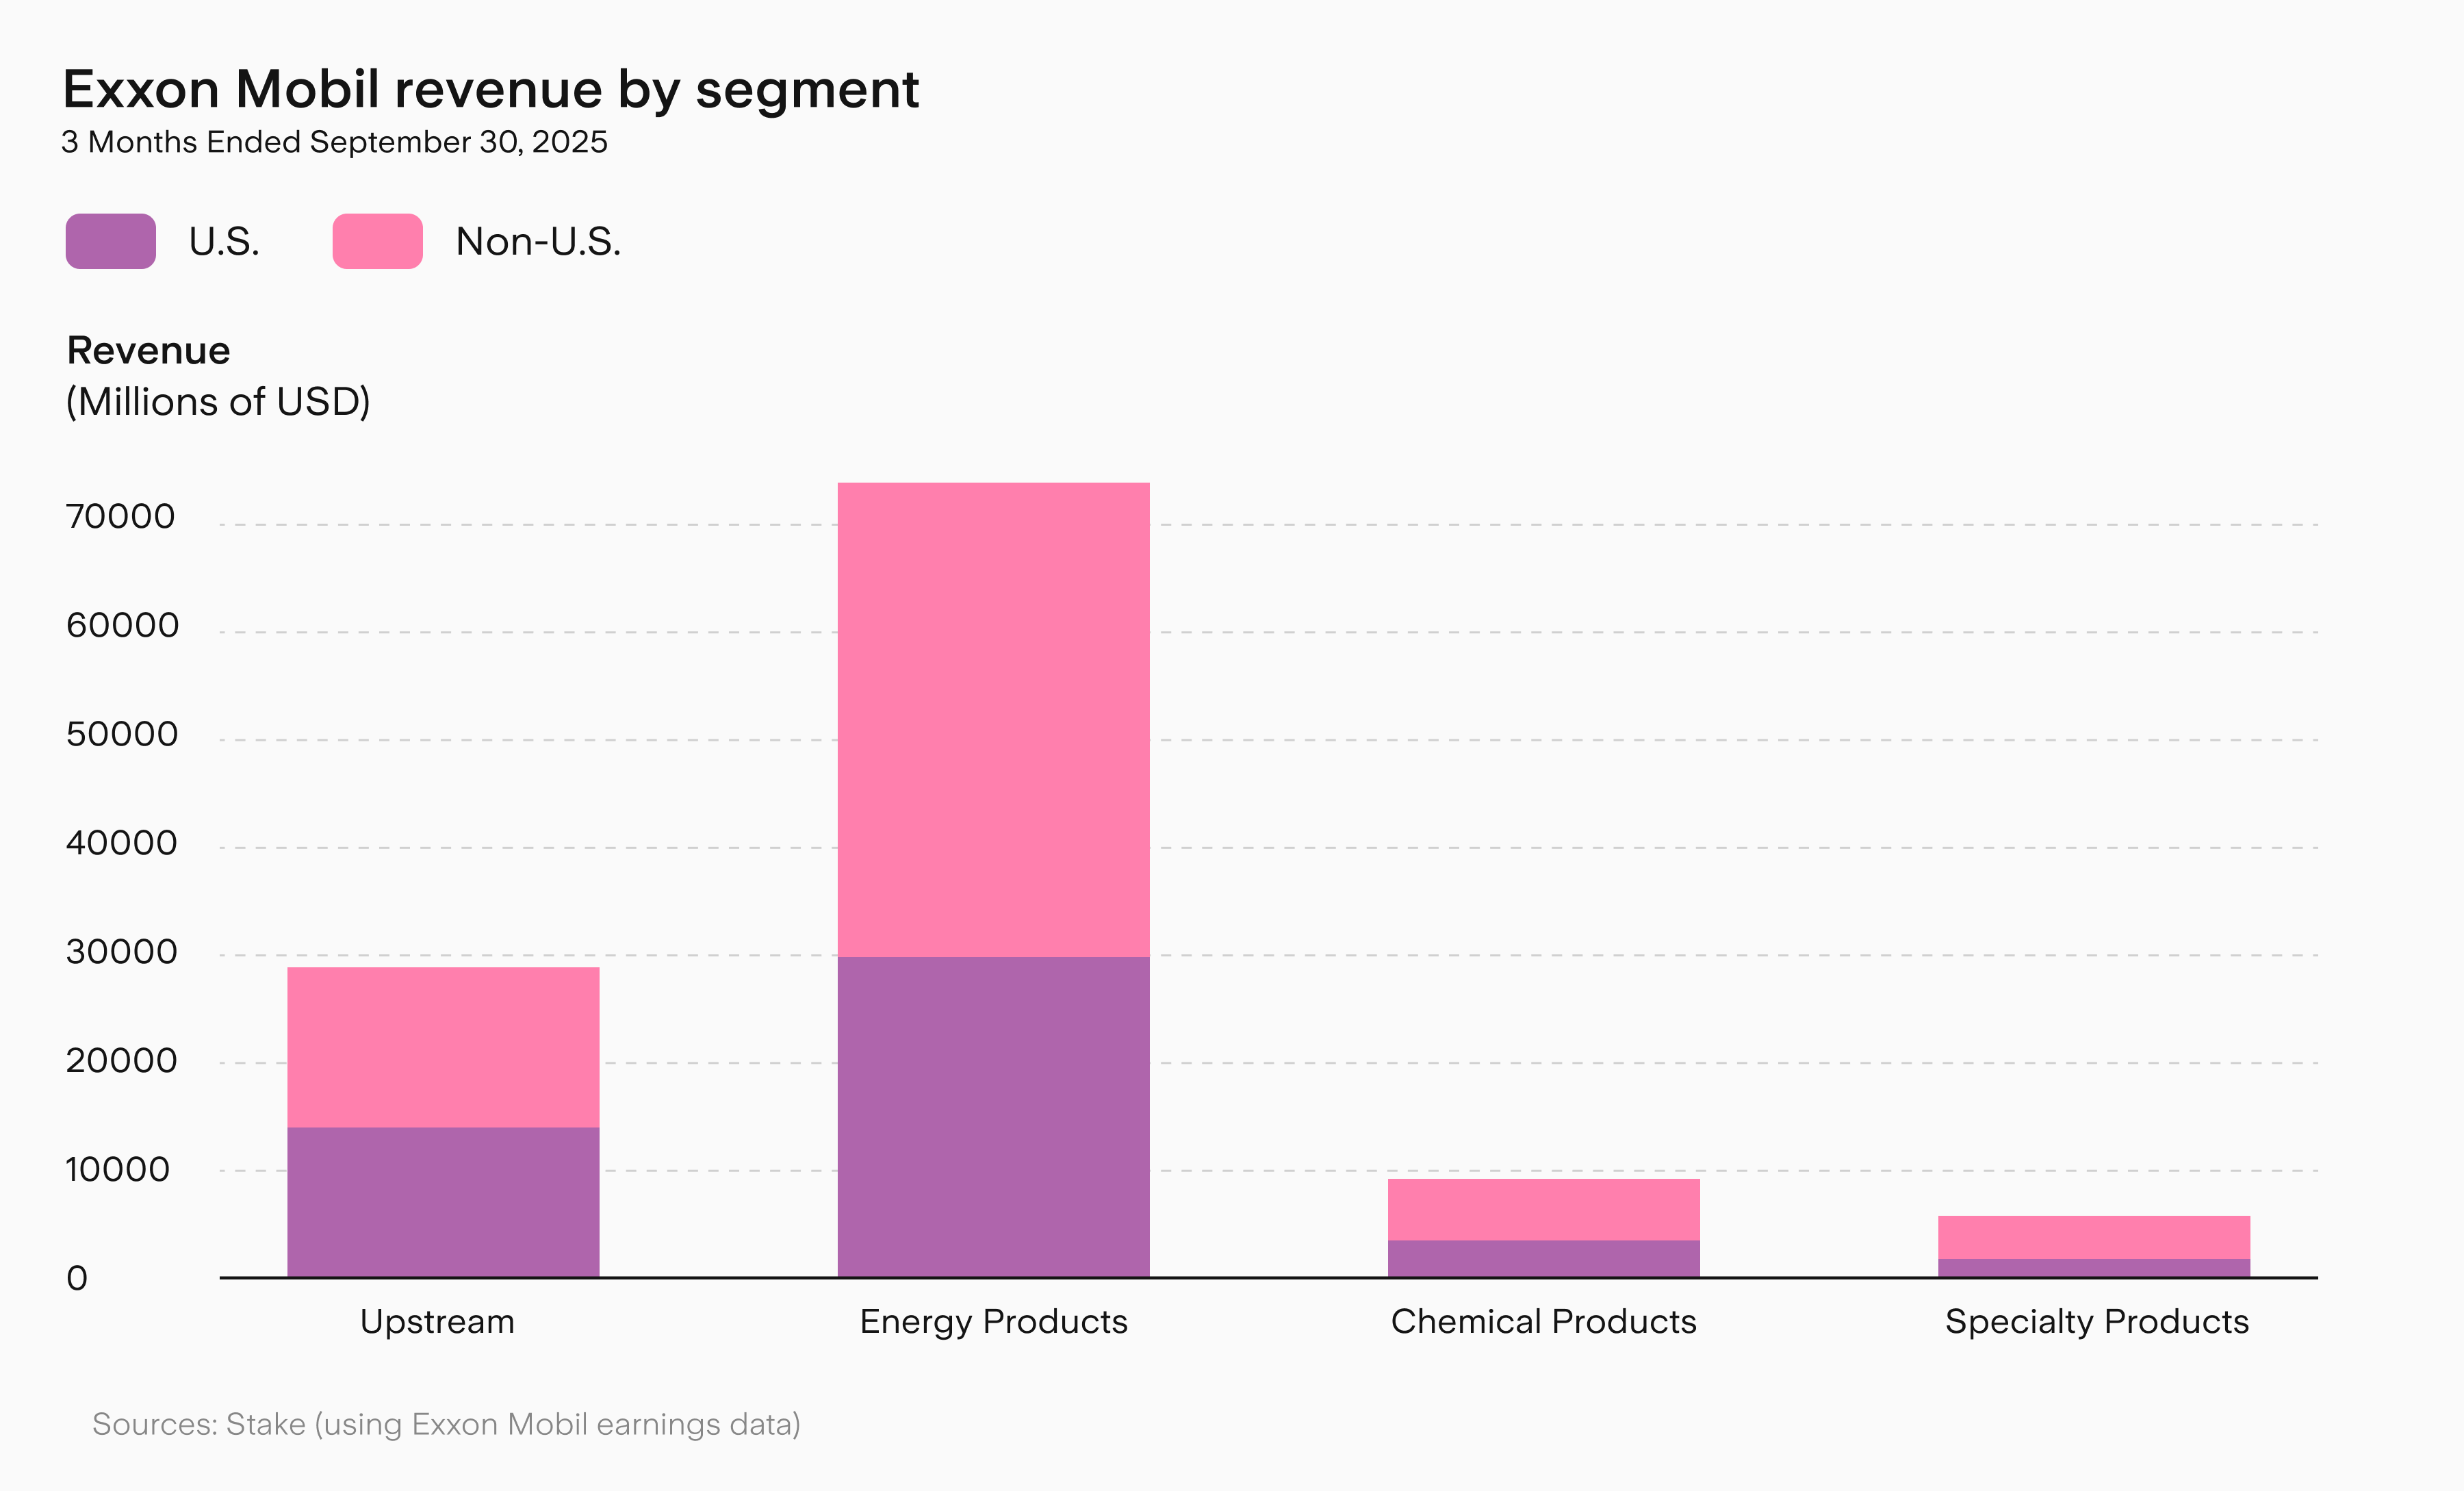
While oil and gas – its upstream and energy products segments – remain the company’s biggest earners, Exxon is also one of the world’s largest chemicals producers and, controversially, the number one producer of single-use plastics.
Moves into clean energy too are emerging. It’s constructing what could soon be the world’s largest low-carbon hydrogen and ammonia plant in Texas. A deal with Japan’s Marubeni Corporation will see 250K tonnes of ammonia shipped to power plants in Japan to help reduce pollution.
Investment into new areas has paid off. Despite oil prices falling almost 20% in 2025, Exxon Mobil’s share price hit a 52-week high in December, signalling a clear move away from being a pure-play oil stock.
Crude financials
Exxon Mobil’s balance sheet remains strong, though margins have taken a hit as oil and gas prices continue to decline.
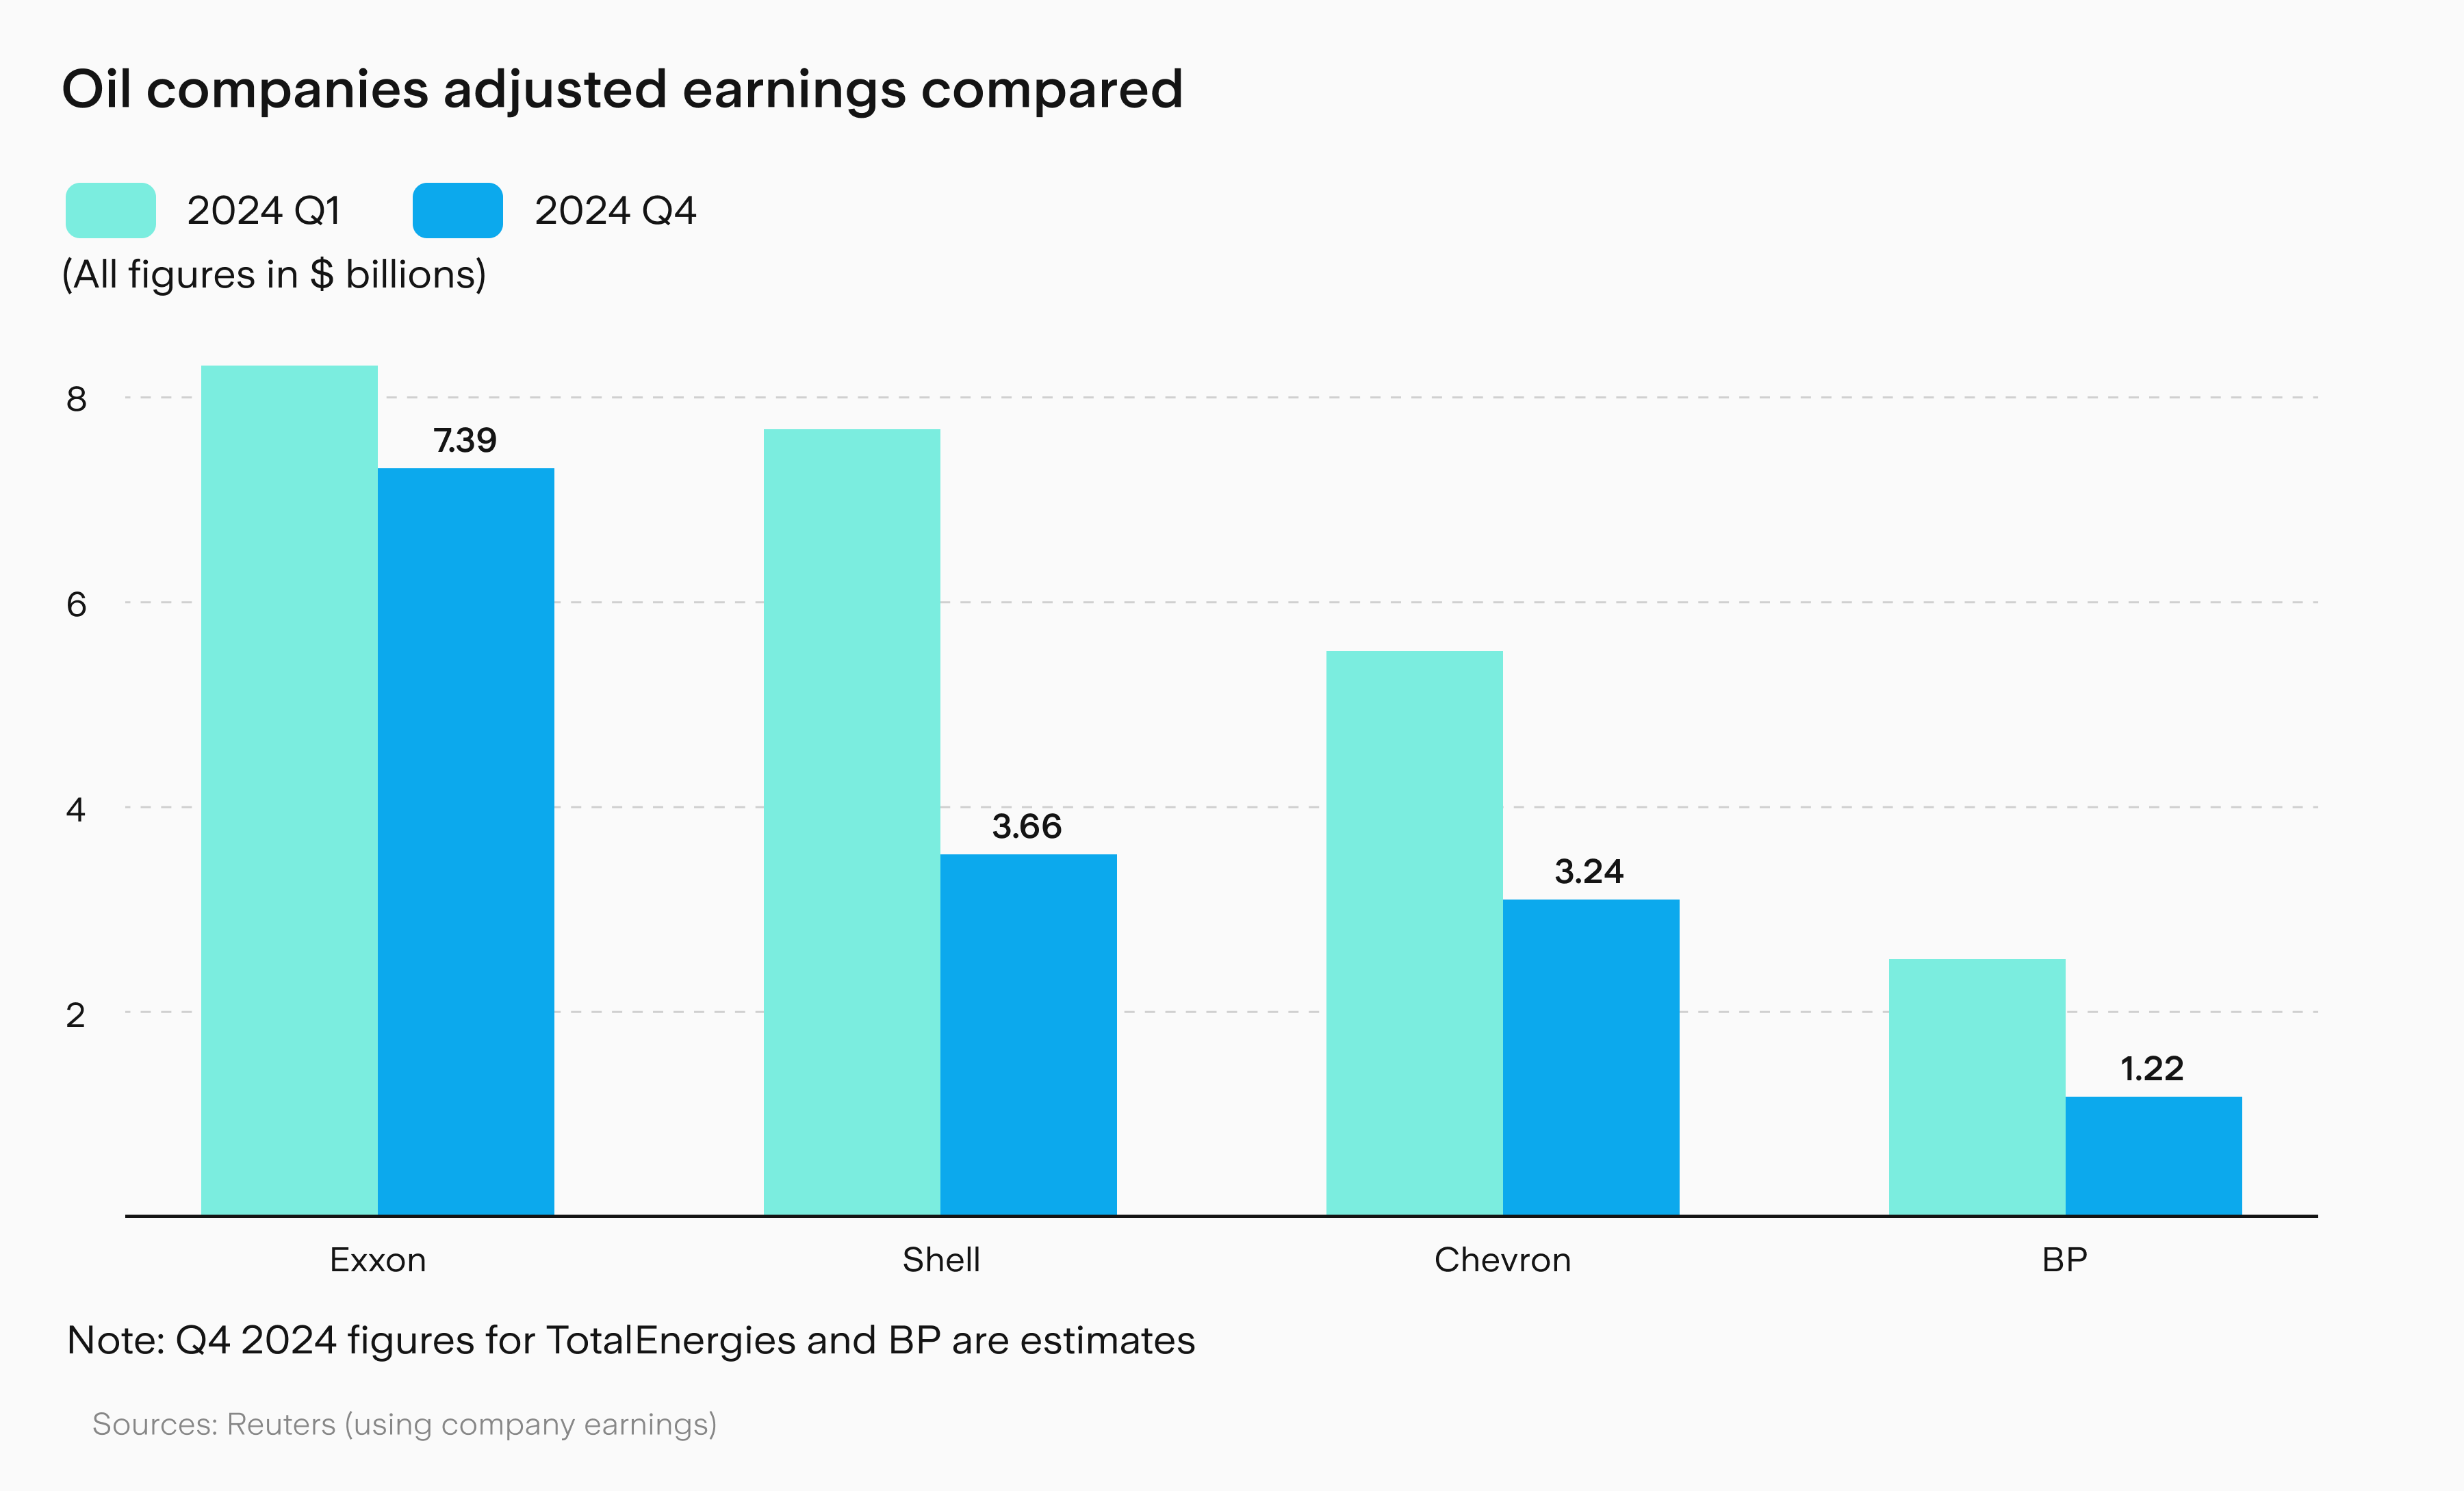
In the most recent period (Q3 FY25), Exxon Mobil delivered earnings of US$22.3B between January and September, down 14% from the year before. Earnings per share (EPS) came in at US$1.76 for the quarter, compared with US$1.92 a year earlier.
Quarterly revenue fell 5% to US$85.3B. Despite the year-on-year decline, the results beat expectations.
Weaker crude prices, depreciation and higher growth costs were expected to weigh on the bottom line. The surprise came from record output in Permian and Guyana.
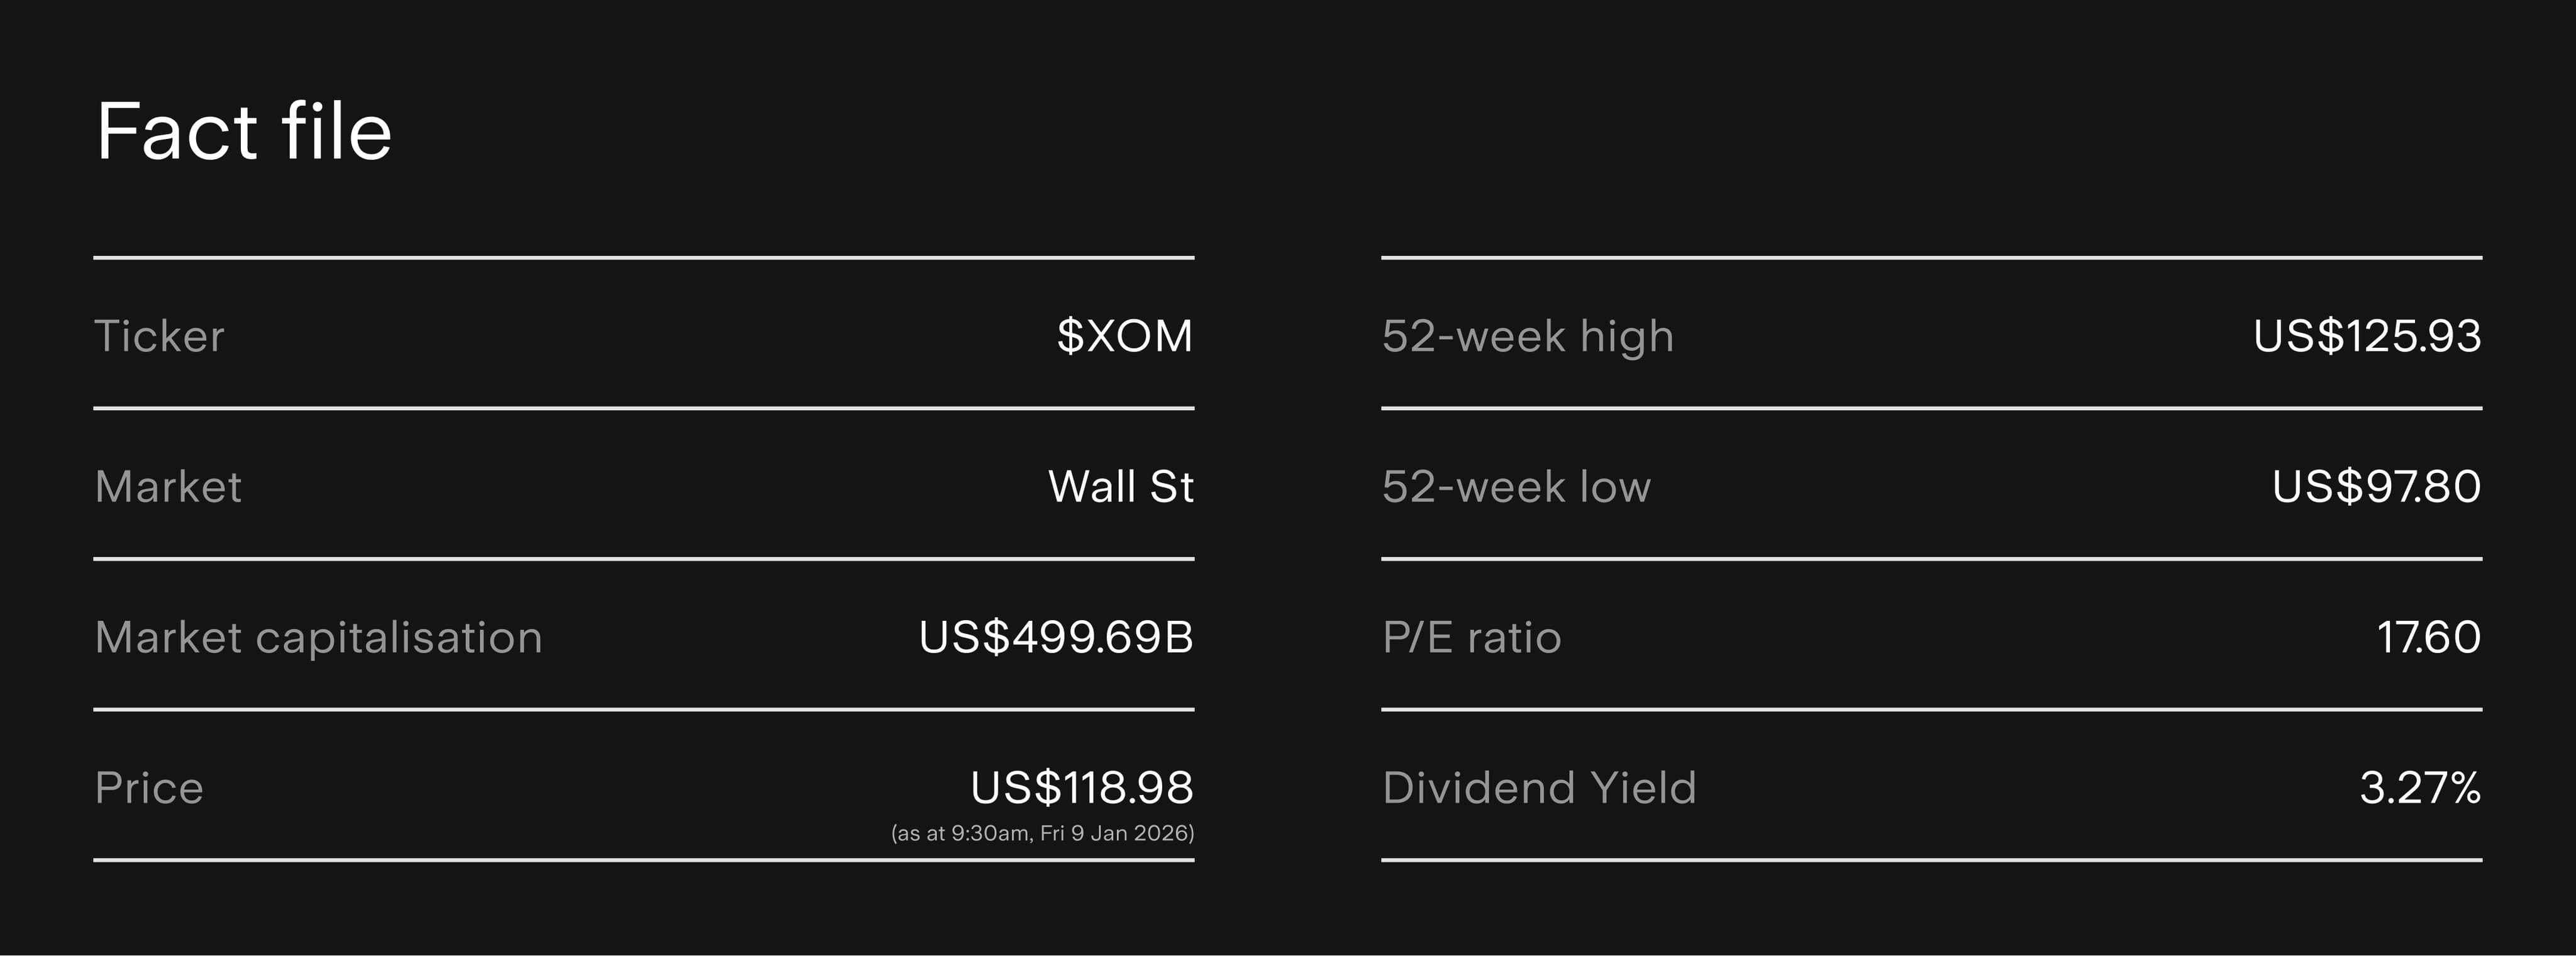
Notably, Exxon remains one of the top dividend payers on Wall St. A dividend yield of around 3.6% and a US$20B annual share buyback program appear durable even in a lower-price environment. The company has now raised its dividend for 43 consecutive years, reinforcing its status as a cornerstone income stock.
Drill, baby
Exxon has upgraded its growth outlook through to 2030, driven largely by higher output from the Permian, Guyana and LNG assets.
It now expects earnings growth of US$25B by 2030 compared to 2024, and cashflow growth of US$35B. Crucially, these targets are expected to be met through efficiency rather than higher capex.
The Permian Basin sits at the centre of this strategy. The acquisition of Pioneer Natural Resources in 2024 significantly expanded Exxon’s footprint, giving it unmatched scale and efficiency in U.S. shale.
While many producers have slowed drilling in response to falling oil prices, Exxon continues to grow output, confident it can operate profitably at lower breakevens than most peers.
New LNG projects in Papua New Guinea and Mozambique add momentum, while newer businesses, including clean energy, are expected to drive up to US$13B in additional earnings by 2040.
At the same time, it’s pulled back on cost-intensive refining. The sale of its Fos oil refinery in France in 2024, significantly reduced its European footprint and signals a retreat from downstream to focus on more profitable upstream businesses in Asia and America.
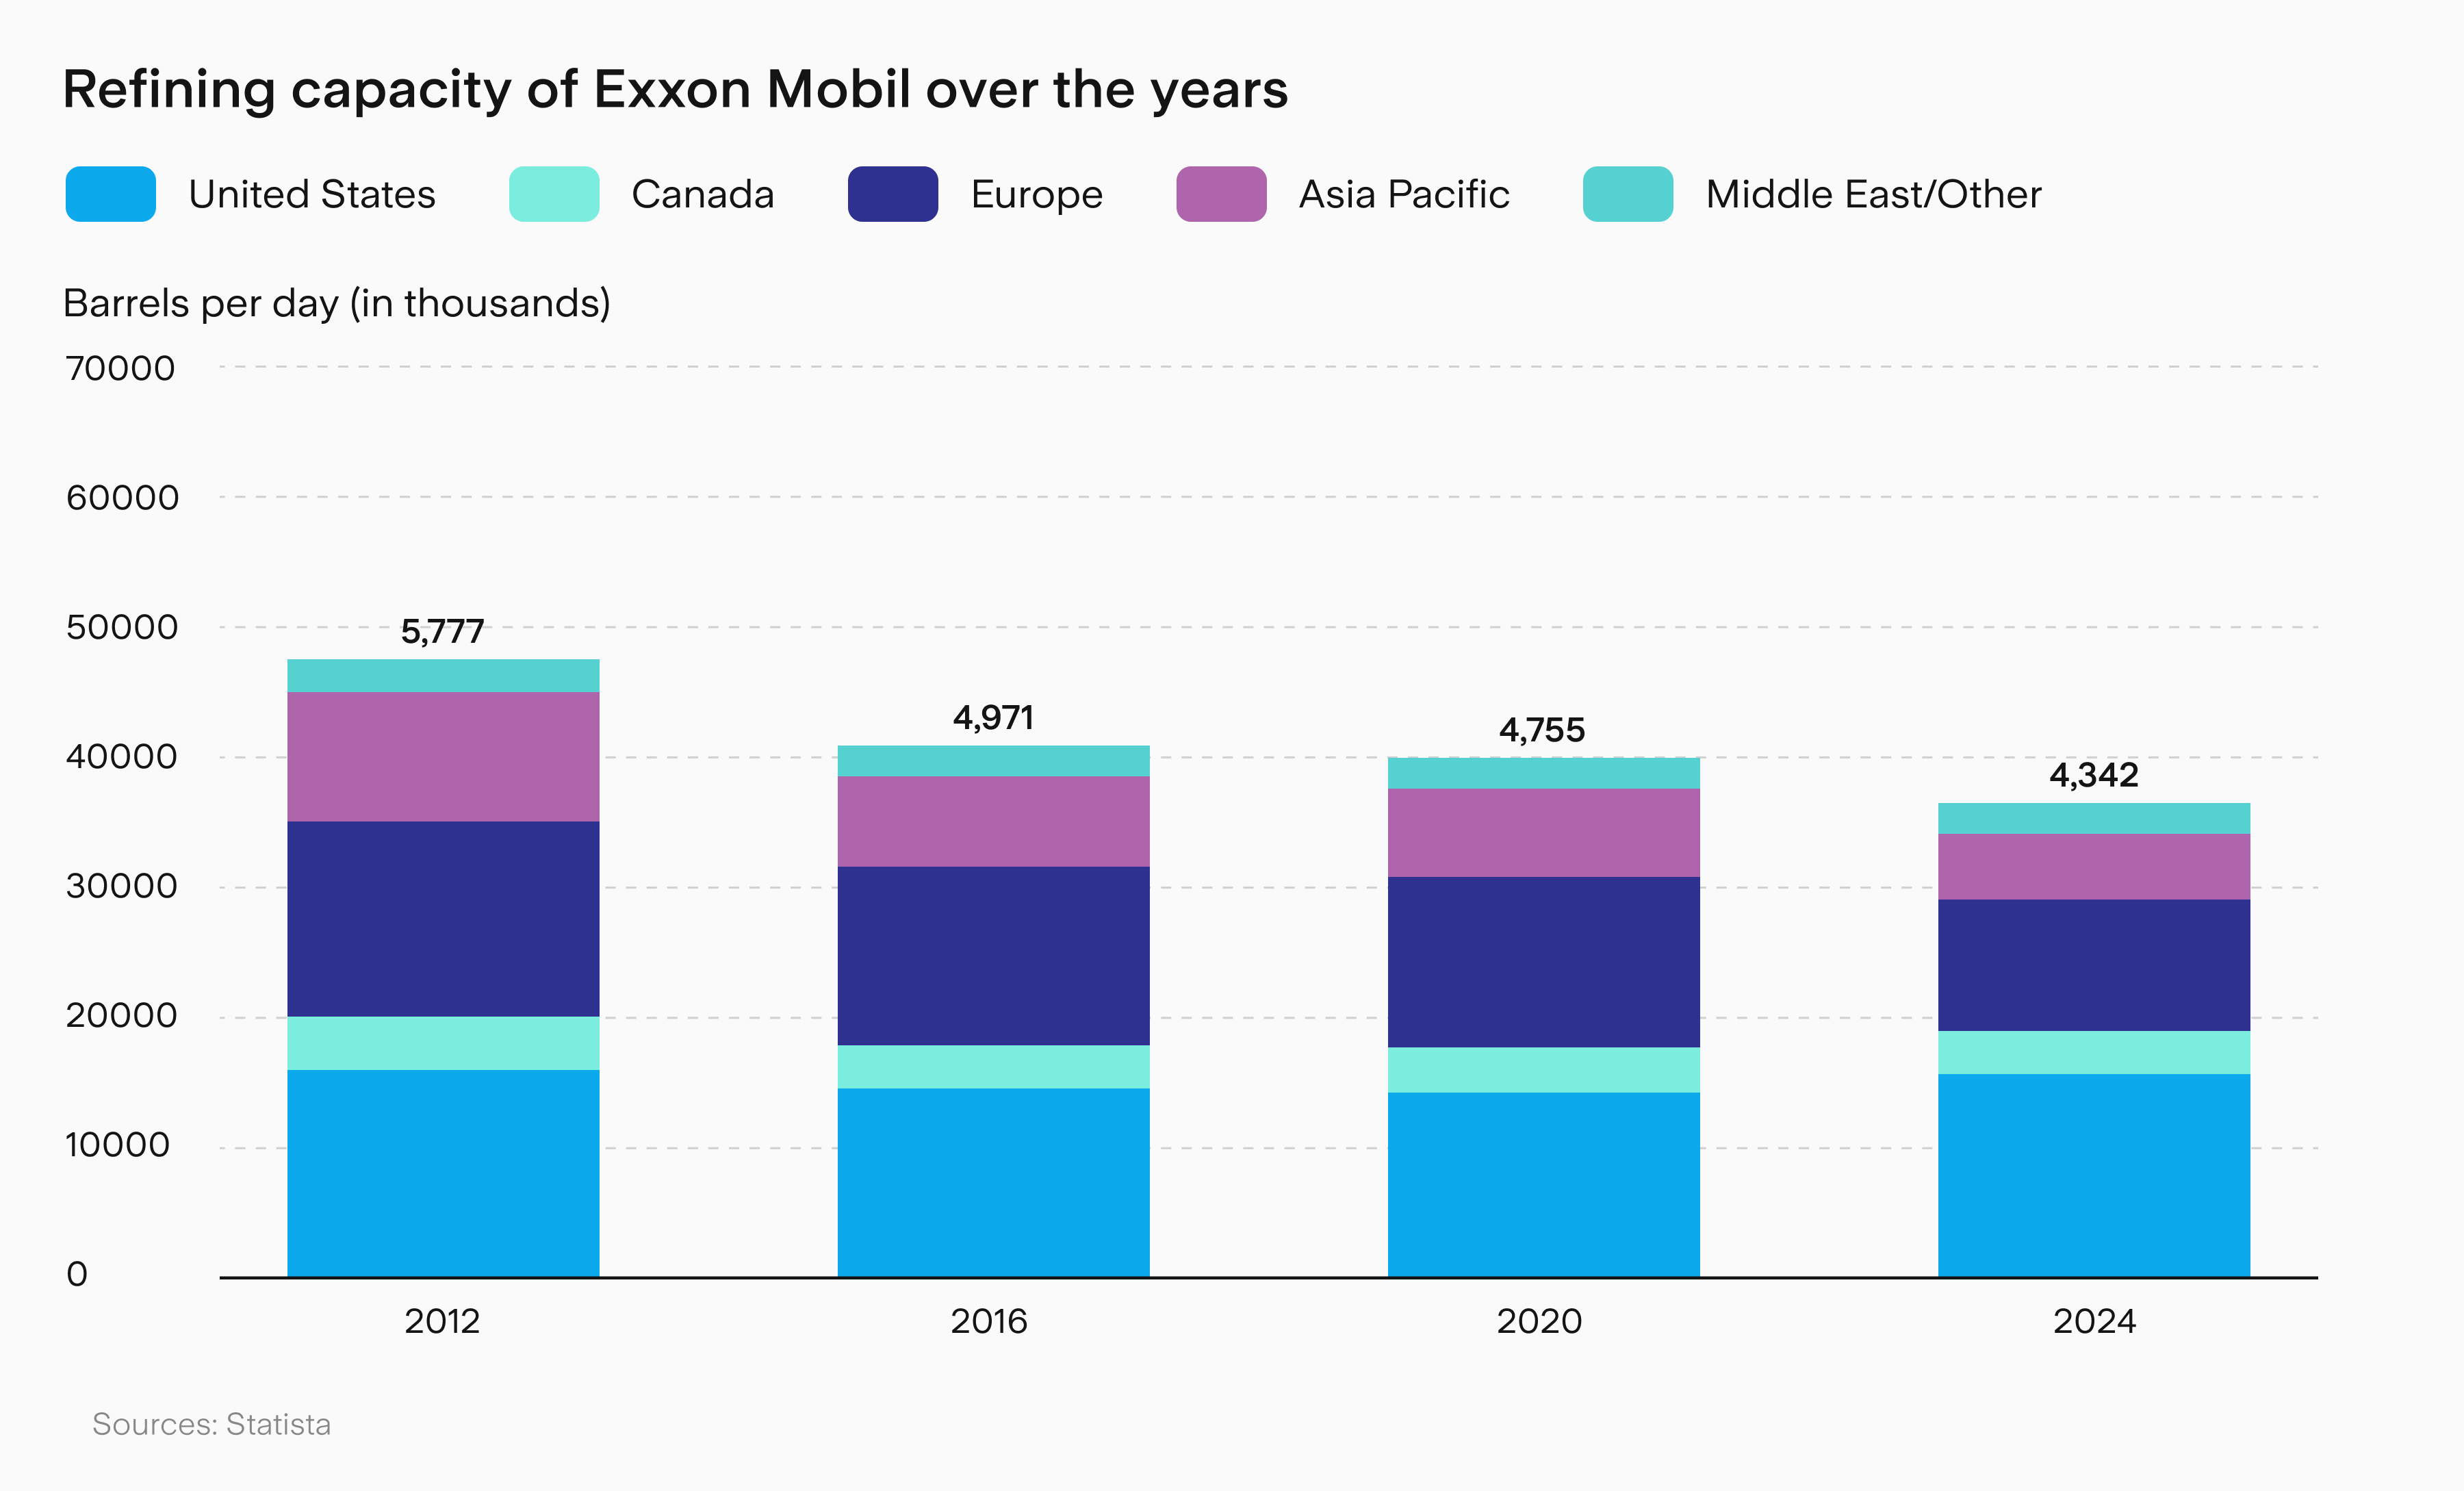
That reshuffling has left Exxon flush with excess cash. With US$145B in surplus cash flow expected by 2030, a re-entry into Venezuela isn’t off the table.
Is $XOM a buy or sell?
Exxon is no longer just a leveraged bet on oil prices. It’s an integrated energy business with the scale and balance sheet to generate cash across the cycle.
While lower crude prices and weak chemical margins pose near-term headwinds, the company continues to grow production, beat earnings expectations and return capital to shareholders.
Exposure to high-quality assets in the Permian and Guyana provides long-term visibility, while financial discipline limits downside risk.
Analysts are relatively optimistic. Of 29 analysts covering the stock, 13 consider it a ‘hold’ at current prices while 16 are a ‘buy’ or ‘strong buy’, according to LSEG data.
Still, the company remains highly exposed to oil and gas price volatility, and environmental concerns and controversies will continue to be a risk. Investors should approach with a long-term view in mind.
This is not financial advice nor a recommendation to invest in the securities listed. The information presented is intended to be of a factual nature only. Past performance is not a reliable indicator of future performance. The author of this article and other employees of Stakeshop Pty Ltd may hold positions or have financial interests in the company (or companies) discussed above. As always, do your own research and consider seeking financial, legal and taxation advice before investing.
Senior Markets Commentator
Kylie Purcell is an investments analyst and finance journalist with over a decade of experience covering global markets, investment products and digital assets. Her commentary has been featured in publications including the Australian Financial Review, Yahoo Finance and The Motley Fool. She has a Masters Degree in International Journalism from Cardiff University and a Certificate of Securities and Managed Investments (RG146).
Subscribe
By subscribing, you agree to our Privacy Policy.